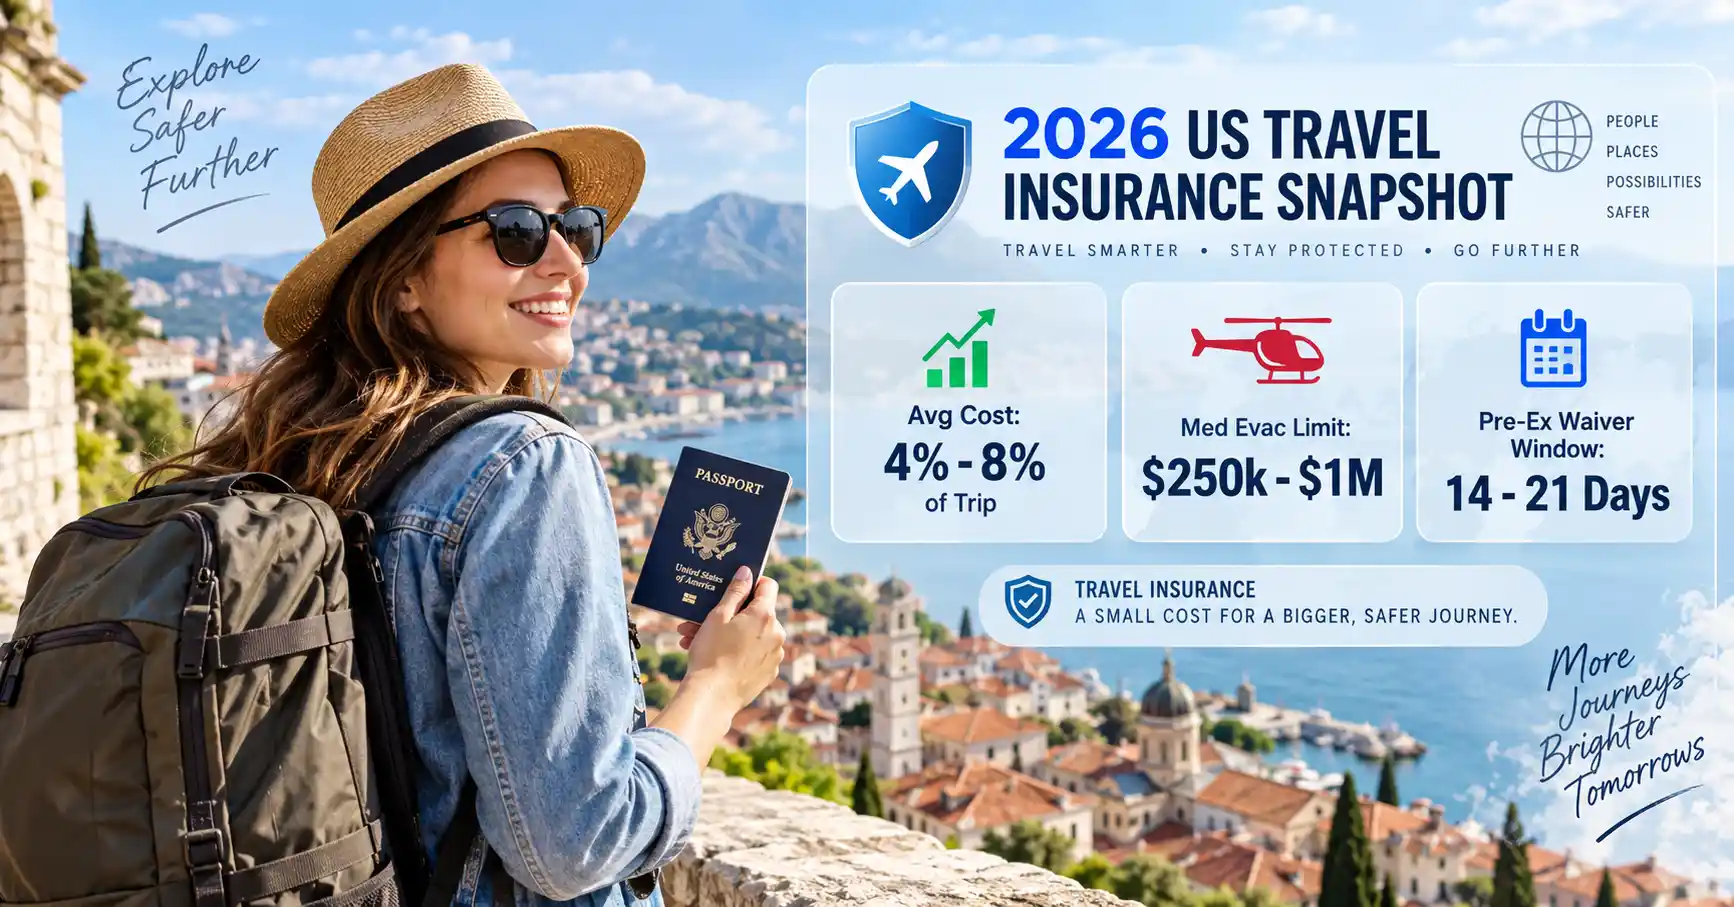
Finding the best travel insurance requires navigating complex exclusions, strict deadlines, and hidden fees. As an industry expert, I often see travelers devastated by out-of-pocket medical bills because they relied on basic credit card perks. As international healthcare costs surge in 2026, I will break down exactly what you should expect to pay, the loopholes to avoid, and how to secure ironclad protection.
Key Takeaways
- Average 2026 Premiums: Comprehensive travel coverage generally runs 4% to 8% of your prepaid, non-refundable trip costs, scaling to 10% to 14%+ for travelers over age 65.
- The “Look-Back” Trap: Standard policies scrutinize your medical records for 60 to 180 days prior to purchase. To secure a Pre-Existing Condition Waiver, you must buy your policy within 10 to 21 days of your initial trip deposit.
- Medical Evacuation Benchmarks: Emergency international evacuation from remote destinations or cruise ships currently averages $50,000 to over $250,000, underscoring the need for high-limit primary medical coverage.
- Cancel For Any Reason (CFAR): This upgrade must be purchased at the time of initial booking, adds roughly 40% to 60% to your base premium, and typically refunds only 50% to 75% of your canceled expenses.
Quick Summary Table
| Policy Type | Best Suited For | Estimated 2026 Cost | Core Coverage Focus |
| Comprehensive Travel Insurance | Most international vacations & cruises | 4% – 8% of total trip cost | Trip cancellation, interruption, primary medical, and baggage loss |
| Travel Medical & Evacuation | Expats, digital nomads, & long-term travelers | $3 – $8 per day | Purely health emergencies and repatriation (no cancellation benefits) |
| CFAR Upgrade | Travelers with highly unpredictable schedules | +40% – 60% on top of base premium | Proactive cancellations for non-covered reasons |
What Does Comprehensive Travel Coverage Cost in 2026?
When budgeting for a domestic or international trip, pricing for a standard comprehensive policy hinges primarily on three actuarial factors: the non-refundable, prepaid dollar value of your trip, your destination, and the age of the oldest traveler.
Under standard US underwriting practices, insurers assess risk bands where younger travelers pay substantially lower rates than seniors due to medical claim frequencies. If you operate an independent business and travel frequently for international conferences, understanding deductible thresholds is as critical as managing operational overhead 🔗 [Insert Internal Link to: How to calculate LLC taxes].
2026 Estimated Policy Costs by Age & Trip Value
| Traveler Age Bracket | Trip Cost: $2,500 | Trip Cost: $5,000 | Trip Cost: $10,000 | Typical Medical Limit |
| Ages 18–35 | $105 – $140 | $210 – $280 | $420 – $560 | $50,000 – $100,000 |
| Ages 36–50 | $130 – $175 | $260 – $350 | $520 – $700 | $100,000 – $250,000 |
| Ages 51–64 | $190 – $260 | $380 – $520 | $760 – $1,040 | $250,000 |
| Ages 65–75 | $280 – $390 | $560 – $780 | $1,120 – $1,560 | $250,000 – $500,000 |
| Ages 76+ | $400 – $580+ | $800 – $1,160+ | $1,600 – $2,320+ | $250,000 – $500,000 |
Under US statutory guidelines, standard domestic health policies—including Medicare Part A and Part B—do not cover health services rendered outside US borders. For US citizens traveling abroad, purchasing emergency medical and medical evacuation coverage is not an optional upsell; it represents the only barrier protecting personal liquid assets from catastrophic out-of-pocket medical liabilities.
The Best Travel Insurance Companies Reviewed & Compared
Finding the best travel insurance companies requires separating mass-market marketing from actual claims fulfillment records, financial strength ratings (A.M. Best), and customer support responsiveness.
| Provider | Best For | Medical Evacuation Limit | Pre-Existing Waiver Window | Notable Standout Feature |
| Allianz Global Assistance | Comprehensive global medical & families | Up to $1,000,000 | 14 days from deposit | Direct-to-hospital payment network across 100+ countries |
| Travelex Insurance Services | Family travelers & primary coverage | Up to $500,000 | 15 days from deposit | Children under 17 covered at no additional charge on select plans |
| Seven Corners | Adventure travel & high-limit medical | Up to $1,000,000 | 20 days from deposit | Customizable riders for hazardous sports and remote trekking |
| Nationwide (Travel) | Cruise excursions & severe baggage delay | Up to $500,000 | 21 days from deposit | Dedicated cruise-specific riders with low delay qualification windows |
Allianz Travel Insurance: Best for Comprehensive Global Medical & Epidemic Coverage
Allianz travel insurance stands out in the consumer insurance market primarily due to its proprietary global healthcare assistance infrastructure. Unlike insurers that outsource emergency coordination to third-party administrative firms, Allianz manages its own international medical assistance teams.
- Pros: Highly streamlined mobile app for real-time paperless claims filing; comprehensive epidemic-related illness coverage; generous children-included pricing structures on family plans.
- Cons: Strict exclusions on high-risk adventure sports (e.g., mountaineering, backcountry skiing) without an added rider; cancellation claims require extensive documentation and proof of loss.
Travelers Insurance vs. Specialized Travel Policies: Understanding the Distinction
A frequent consumer misconception involves searching for travelers insurance when seeking international trip protection. The Travelers Companies (commonly known as Travelers Insurance) is one of the largest property and casualty insurers in the United States, specializing in commercial business lines, homeowners, personal auto, and umbrella liability.
While a homeowners or personal property policy through Travelers may extend partial personal property liability or off-premises theft protection while you travel domestically, it does not function as a comprehensive travel policy. It lacks trip cancellation benefits, trip delay compensation, missed connection allowances, emergency medical treatment overseas, and emergency medical repatriation. To obtain these protections, travelers must contract through dedicated travel underwriters rather than standard domestic casualty carriers.
Pros & Cons of Purchasing Standalone Travel Insurance
Evaluating whether to secure standalone protection versus relying on premium credit card benefits requires a direct cost-benefit analysis.
Pros
- Substantial Emergency Evacuation Limits: Dedicated standalone policies offer medical evacuation limits exceeding $500,000 to $1,000,000, ensuring air-ambulance transport from remote foreign locations.
- First-Dollar Primary Medical Coverage: Shields domestic health plan deductibles and avoids the requirement to exhaust employer-sponsored plans before receiving claim payouts.
- Configurable CFAR Protections: Provides the flexibility to cancel reservations for personal anxieties, political uncertainties, or scheduling disruptions outside standard covered peril lists.
Cons
- Added Upfront Expense: Increases total vacation or business travel outlay by 4% to 14% depending on age and trip valuation.
- Rigid Documentation Standards: Reimbursed expenses require strict itemized receipts, doctor certifications, and written carrier delay verification.
- Exclusion Complexity: Hazardous activities, uncertified tour operators, and mental health-related cancellations are frequently excluded from baseline coverage forms.
How to Choose the Best Travel Insurance Policy for Your Trip
Selecting the best travel insurance for your upcoming itinerary requires aligning policy specifications with your actual financial exposure:
- Calculate Truly Non-Refundable Expenses: Only insure expenses that cannot be recovered via airline credits, hotel refund policies, or tour operator waivers. Insuring refundable legs needlessly inflates your policy premium.
- Review Medical Limits for Transoceanic Travel: Target a minimum of $100,000 in primary emergency medical and $250,000 to $500,000 in emergency medical evacuation, particularly for cruise itineraries or transcontinental travel where medical transfer costs escalate rapidly.
- Audit the Timetable for Waivers: Mark your calendar immediately upon paying your initial deposit to secure your pre-existing condition waiver within the required 10-to-21-day timeline.
Frequently Asked Questions
What does travel insurance typically cover?
Comprehensive travel insurance covers prepaid, non-refundable trip expenses lost to covered cancellations, severe delays, and baggage loss. It also pays for emergency medical care and international medical evacuation during your travels.
Is travel insurance mandatory for international trips?
Travel insurance is not federally mandated by the US government, but several foreign countries require proof of travel medical coverage for visa entry. Regardless of mandates, it is critical because domestic health insurance—including Medicare—does not cover healthcare abroad.
When should you buy travel insurance?
You should purchase travel insurance within 10 to 21 days of making your initial trip deposit or flight reservation. Buying within this early window ensures you qualify for the Pre-Existing Condition Exclusion Waiver and optional Cancel For Any Reason (CFAR) coverage.
Does credit card travel insurance replace a standalone policy?
Credit card travel protection provides basic reimbursement for trip delays and lost luggage, but it rarely offers sufficient primary medical or high-limit evacuation coverage. For international voyages, cruises, or remote excursions, a standalone comprehensive policy is strongly advised.
Can you cancel a trip for any reason and receive a full refund?
Standard policies only reimburse cancellations triggered by strictly defined, covered perils like severe illness, death in the immediate family, or severe weather. To cancel for personal reasons or anxiety, you must purchase a Cancel For Any Reason (CFAR) rider, which reimburses 50% to 75% of your non-refundable expenses.
Expert Verdict: Final Recommendation for 2026 Travelers
Selecting the best travel insurance comes down to protecting both your upfront travel investment and your personal health from catastrophic international liabilities. Never treat travel coverage as an interchangeable commodity or rely on passive credit card perks when traveling abroad.
For standard single-trip international journeys, prioritize comprehensive plans with first-dollar primary medical coverage of at least $100,000 and evacuation limits starting at $250,000. Book your policy within two weeks of your first deposit to lock in your pre-existing condition protections. By matching your policy directly to your destination risk, age bracket, and non-refundable trip costs, you can travel abroad with verifiable, institutional-grade protection.